Separating the Money: A Grounded Guide to Sole Proprietor Banking
If you just read our guide on The $400 Rule , you know that crossing that threshold means your side hustle is officially a business in the eyes of the IRS . You are tracking expenses, stashing away a percentage for taxes, and stepping into your role as an independent contractor .
But as the checks start arriving, a new, practical hurdle appears. You go to deposit your client’s money and realize it’s landing right next to your grocery money, your rent cash, and your morning coffee fund.
When you dig into traditional corporate banking advice, everything assumes you are a formal LLC with complex legal formation documents . It can leave you wondering: Can a sole proprietor even get a business account? Do I have to use my personal bank? How do I stop this financial blur?
Let’s cut through the noise and look at a simple, step-by-step roadmap for keeping your business money completely separate—without the administrative headache.
Why Co-Mingling is a Solo Business Trap
When you operate as a sole proprietor, you and your business are technically the exact same legal entity. You don’t have the “corporate veil” of an LLC protecting your personal property.
Because of this, many freelancers assume there is no point in having separate bank accounts.
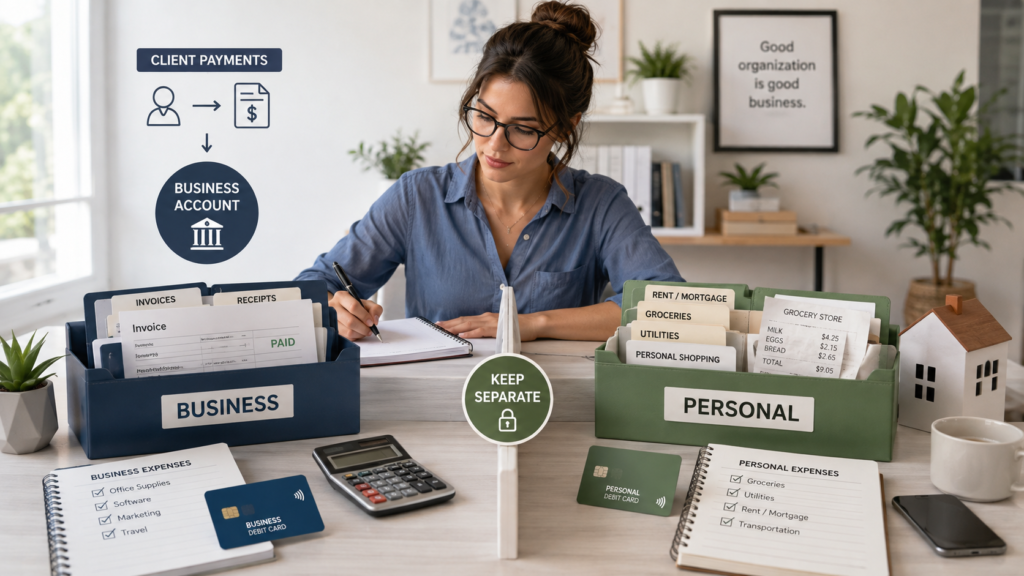
While it might not be a legal requirement for a sole proprietor, keeping your money mixed together (co-mingling) creates two massive problems:
- The “Audit Nightmare” Scenario: If the IRS ever audits your tax return, they will ask for proof of your business deductions. If your business software, client dinners, and car expenses are all tangled up in a personal account next to your personal transactions, proving what was a “legitimate business expense” becomes incredibly stressful. Clean accounts equal short, painless reviews.
- Financial Blindness: When all your cash lives in one pool, you can’t accurately see if your business is actually making money. You might feel flush with cash because a client just paid you $1,500, forgetting that 30% belongs to taxes and your personal car insurance payment is due tomorrow.
Do You Need a Personal or Business Account?
As a sole proprietor, you have two practical paths to separate your cash:
Path A: The Second Personal Account (The Budget Route)
Many retail banks allow you to open a secondary checking account under your own name for free. If you are operating strictly under your legal name (e.g., Sarah Jenkins, Freelance Consultant), you can use this second account exclusively for your business. All client payments go in; all business software and expenses come out. It costs nothing and takes five minutes to set up online.
Path B: A True Business Checking Account (The Professional Route)
If you want to open an account that uses a distinct business name (e.g., Summit Creative Studios), or if you want access to specialized business banking tools, you need a dedicated business checking account .
Your Banking Checklist: What to Bring to the Bank
If you choose to open a formal business account as a sole proprietor, walk into the branch (or open the online application) with these exact items ready :
- Your Government-Issued ID: A valid driver’s license or passport .
- Your Tax Identification Number: As a sole proprietor, this can simply be your Social Security Number (SSN) . However, you can also generate a free Employer Identification Number (EIN) on the IRS website in minutes if you prefer not to give out your SSN to clients on W-9 forms . Banks accept either .
- A Business License or DBA Certificate: If you are operating under a trade name that doesn’t include your legal last name, the bank will want to see your registered DBA (Doing Business As) or Fictitious Name Certificate from your city or state .
- An Opening Deposit: Usually a small amount, often between $25 and $100, to fund the account on day one .
The Three-Account Framework
Once your accounts are open, organize your money using the Three-Account Framework. This completely automates your budgeting and ensures you never accidentally spend your tax money:
- The Business Hub (Checking): Every single dollar a client pays you must land here first. Every business expense (software, supplies, advertising) is paid out of this account.
- The Tax Vault (Savings): Every time a payment clears into your Business Hub, immediately transfer 25% to 30% into this account. Do not touch it. This money belongs to the IRS, and keeping it isolated ensures you have zero stress when quarterly or annual taxes are due.
- Your Personal Life (Personal Checking): Once a month or every two weeks, write yourself a “paycheck” by transferring your remaining profit from the Business Hub to your regular personal checking account. This is your money to spend on life, completely guilt-free.
Grounded Rules for Daily Maintenance
To keep this system working smoothly, follow these three grounded habits:
- Never use your business card at the grocery store. If you accidentally pull out the wrong card for personal expenses, don’t panic. Simply transfer the exact amount from your personal account back into your business account to keep the ledger square, and note it down.
- Audit your accounts once a month. Spend 15 minutes on the first of every month matching your invoices against your business account deposits.
- Keep receipts digitally. You don’t need a shoebox of paper. Take a quick photo of physical receipts and drop them into a dedicated folder on your computer or cloud drive labeled by the tax year.
Final Thoughts
Separating your money is the ultimate act of respect for your own time and hard work. It takes the guesswork out of your finances, shields you from tax-season panic, and gives you a crystal-clear look at your business growth.
Get your accounts organized this week, establish your boundaries, and build a sturdy foundation for everything your hustle will become.
Are you leaning toward using a separate personal account or taking the leap into a formal business bank account? Let us know your strategy in the comments below!
The Site cannot and does not contain financial, tax, or legal advice. The information contained on this website is provided for general informational and educational purposes only and is not a substitute for professional advice. Accordingly, before taking any actions based upon such information, we encourage you to consult with the appropriate professionals. We do not provide any kind of financial and tax advice. THE USE OR RELIANCE OF ANY INFORMATION CONTAINED ON THE SITE IS SOLELY AT YOUR OWN RISK.